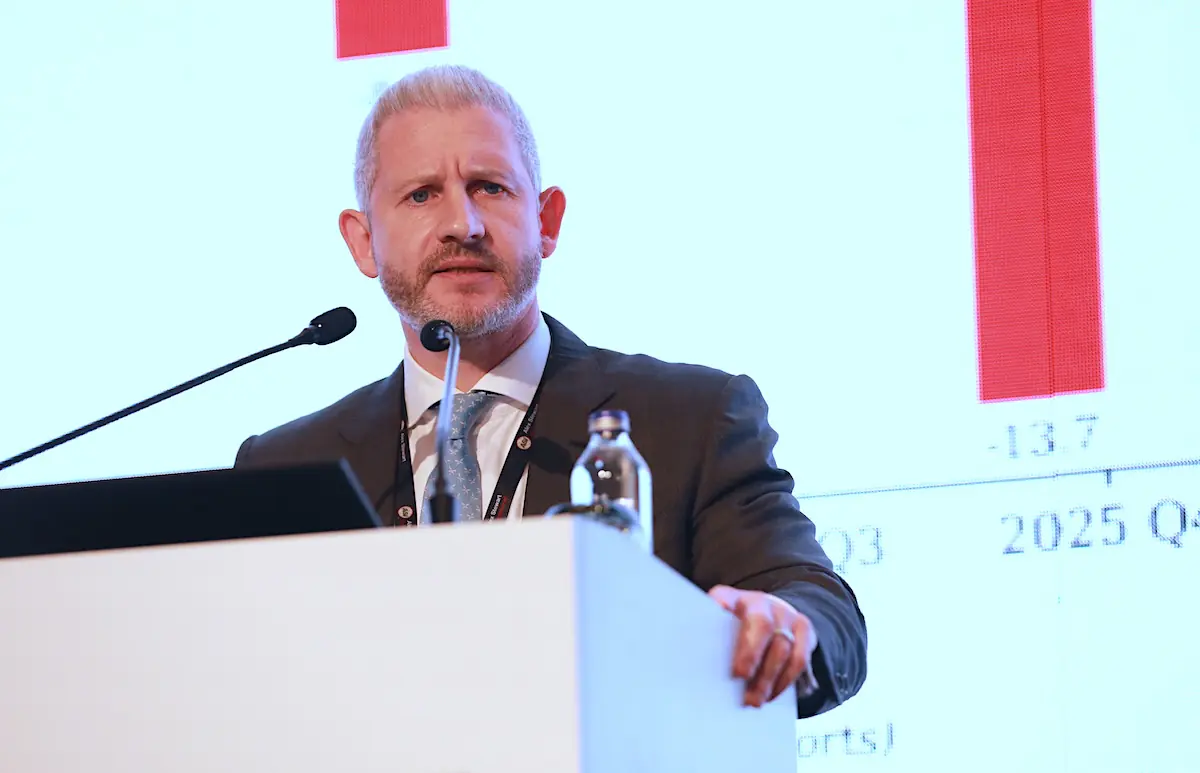
World Steel Dynamics (WSD) expects global steel demand in 2026 to be well below the World Steel Association’s forecast, as consumption in China falls faster than anticipated.
Visible steel consumption in China fell by almost 6.5% in January–August, WSD CEO Philip Englin said in his keynote address at the Steel Networking Summit in Istanbul. A Kallanish correspondent attended the event. “It looks like a 2% decline is not what we are going to see. I think it will be significantly stronger,” Englin forecast.
According to the WSD chief, international hot-rolled coil prices have largely depended on Chinese exports over the past three to four years. As a result, steelmakers both in China and elsewhere are losing money.
China’s exports of finished steel edged down this year. However, shipments of semi-finished products have risen again in 2026. Englin said this increase was mainly due to Iranian semis being replaced in international markets, and showed how quickly China can fill any supply shortfall.
Outside China and India, steel demand has barely grown over the past decade and “is basically just absorbing the net exports from China,” Englin said. Demand is being affected by the conflict in the Middle East. India and, to a lesser extent, Vietnam are the only regions where consumption is increasing significantly.
Developing economies now have little chance of following the traditional path of building up steel and manufacturing industries: China is capturing global manufacturing just as it previously did the steel sector, Englin said. Some estimates put net Chinese exports of steel-containing goods at 130–150 million tonnes, in addition to finished steel exports.
Support for steel prices from the raw materials market has also weakened: iron ore has fallen significantly from its peak and faces new challenges, Englin said. A recent rise in coking coal prices, driven by mining restrictions in China, has gradually faded.
In the US, 50% tariffs have led to the highest sustained prices ever seen in the market, but the resulting price gap is once again encouraging imports. Englin said the annualized rate of flat steel imports had approached 8 million tonnes, up from about 5.5 million tonnes, while slab shipments in recent months had risen to nearly 8 million tonnes annualized, against a normal level of 3.5–4 million tonnes. This creates “huge arbitrage opportunities for rerollers.”
Englin said it was “almost astonishing” that prices in Europe had not risen more amid lower imports. This could be due to weak demand or destocking, he said. At the same time, underlying demand indicators are not “signaling any kind of catastrophe.” WSD still sees scope for prices of European-made steel to rise: imports are declining, while supply is being cut “quite sharply” — provided the tariff-rate quota system works.
In 2027, Englin estimates that downward pressures will outweigh the upward ones. These include accelerating inflation, rising energy prices and higher exports from China. He considers stimulus for steel-intensive industries and production restrictions in China unlikely. However, with “acceptable” demand growth outside China and a small decline in Chinese exports, “we could see another moderate rise in international steel prices,” Englin concluded.
By: Burak Odabaşı, Turkey